 NeuralCapital
Beyond the AI Model: Who Owns the Paying Workflow?
Want to invest in PLTR?
Visit our How to Invest page to get started with platforms like Fidelity or Robinhood.
Artificial intelligence has become remarkably good at demonstrating what it can do. The harder question is who will pay for it, how consistently they will pay, and whether the companies providing it can turn technological capability into durable profits. As investors search for the next beneficiaries of the AI revolution, the distinction between impressive software and commercially indispensable software is becoming increasingly important.
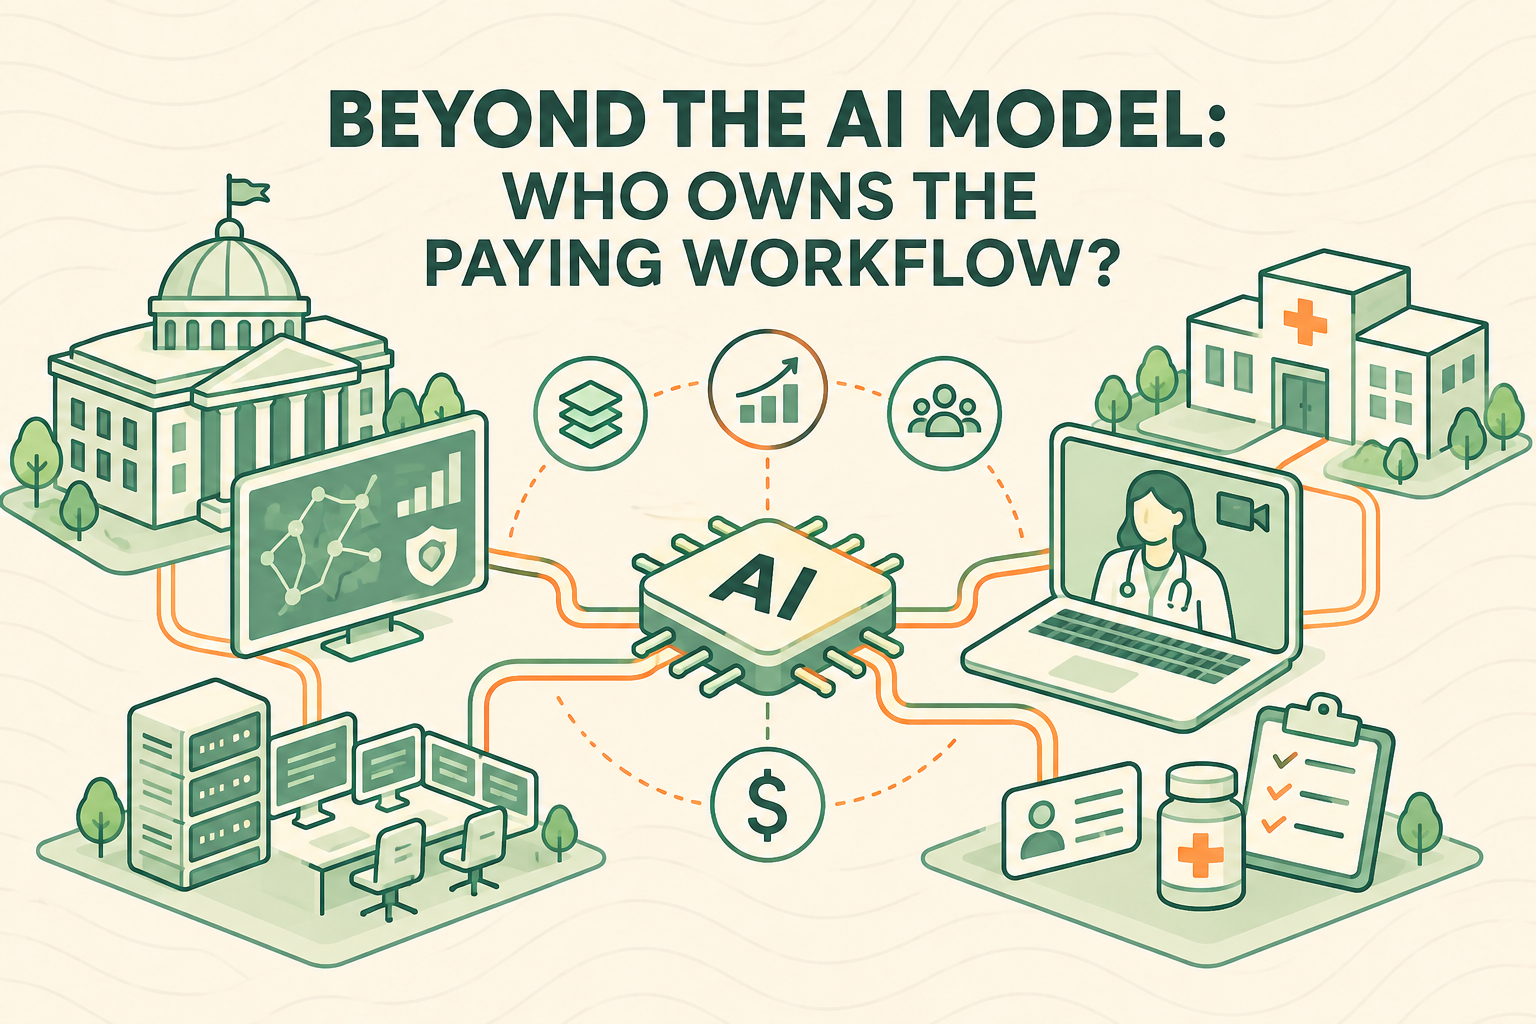
Palantir Technologies and Rocket Doctor AI offer an instructive comparison. Palantir sells sophisticated data and AI platforms to governments and large enterprises, embedding its software in complex institutional operations. Rocket Doctor, a much smaller healthcare technology company, provides physicians with digital infrastructure to operate virtual practices, reach insured patients and participate in established reimbursement systems.
The companies differ enormously in scale, maturity and financial resources. Yet both confront the same commercial question: can artificial intelligence become part of a workflow that already has an economic purpose, an identifiable customer and a mechanism for payment?
The Business Model Matters More Than the Model
The first phase of the AI boom was dominated by technological achievement. More capable language models, sophisticated reasoning systems and expanding computing infrastructure encouraged investors to focus on technical leadership. But technical superiority does not necessarily translate into lasting commercial advantage.
Models can become cheaper, competitors can replicate capabilities and customers can switch providers. The companies that capture enduring value may instead be those connecting AI to activities that organizations already consider essential.
A hospital does not primarily want a language model. It wants patients treated, records maintained and claims processed. A manufacturer wants production schedules improved, equipment failures anticipated and inventory managed. In each case, AI becomes economically meaningful when it improves an activity that already carries costs or generates revenue.
Palantir and Rocket Doctor approach this opportunity from different directions. One begins with the institutional operating system, while the other begins with the physician and the economics of delivering care.
Palantir: The Institutional Operating System
Palantir has spent more than two decades developing software that helps organizations integrate complicated information and make operational decisions. Its early reputation came largely from government and defense work, but the company has increasingly expanded into commercial markets.
Its Foundry platform integrates enterprise information, while its Ontology technology connects that information to real-world business operations. The company's Artificial Intelligence Platform, or AIP, builds upon this foundation, allowing AI systems to interact with organizational data and workflows.
This differs from offering employees a general-purpose chatbot. A manufacturer might use Palantir to identify production bottlenecks, while a logistics company might improve the allocation of resources across its network. The value lies not simply in generating answers, but in connecting those answers to authorized operational decisions.
That integration may also create competitive advantages. Businesses must address security, governance, reliability and accountability before allowing AI to influence consequential activities. Software deeply embedded in these processes can become difficult to replace, particularly when switching platforms would disrupt established operations.
Palantir's latest financial results suggest that customers are increasingly willing to pay for this proposition.
Palantir's Financial Results Demonstrate Commercial Adoption
On November 2, Palantir reported third-quarter 2026 revenue of $2.31 billion, up 96% from the previous year. U.S. commercial revenue increased 148% to $984 million, exceeding U.S. government revenue of $953 million for the first time.
The milestone illustrates how far Palantir has progressed beyond its original government-focused business. Private-sector customers increasingly appear willing to make substantial financial commitments to software intended to improve operational performance.
The company closed 212 deals worth at least $1 million during the quarter, including 107 valued at $5 million or more and 64 worth at least $10 million. These are not merely experimental subscriptions, but significant commercial agreements.
Profitability reinforces the picture. Palantir generated approximately $1.09 billion in GAAP operating income, representing a 47% margin, while adjusted free cash flow reached approximately $1.22 billion. The company ended September with roughly $10.4 billion in cash, cash equivalents and U.S. Treasury securities.
Management raised full-year revenue guidance to approximately $8.53 billion, implying growth of around 91%. Such performance is exceptional for a software company operating at this scale.
Nevertheless, investors must distinguish commercial success from investment value. Palantir's premium valuation reflects substantial expectations for future growth, leaving shareholders vulnerable if expansion slows. Third-quarter U.S. commercial total contract value also grew just 11% year over year, a reminder that new business commitments can fluctuate even when recognized revenue is accelerating.
Palantir has demonstrated that AI-enabled workflows can generate substantial revenue and cash flow. The remaining question is how long its exceptional growth can continue, and how much future success is already reflected in its share price.
Rocket Doctor: Putting the Workflow in the Physician's Hands
Rocket Doctor AI approaches the commercialization problem from a smaller and more specialized starting point. Rather than selling an operating system to a large institution, it provides digital infrastructure intended to help physicians deliver virtual healthcare independently.
The underlying problem is access. Patients frequently struggle to obtain timely medical appointments, particularly in underserved communities. Physicians face administrative burdens involving scheduling, documentation, patient acquisition, billing and reimbursement, making independent practice increasingly complicated.
Rocket Doctor attempts to reduce these obstacles by connecting physicians with patients through a platform that supports virtual consultations and practice administration. Its relationships with insurers and other payers allow eligible medical services to participate in established reimbursement arrangements.
This is an important distinction from AI applications that must persuade customers to purchase entirely new services. Medical care already operates within a substantial payment system involving commercial insurance, Medicare and Medicaid. Rocket Doctor is attempting to make that system more accessible and efficient.
Its AI ambitions sit within this broader proposition. Technology may eventually improve documentation, administrative efficiency and clinical workflows, but the immediate commercial opportunity depends on physicians delivering care and receiving payment.
Where Palantir embeds AI into institutional operations, Rocket Doctor places software in the hands of individual physicians. Both are attempting to make technology useful within activities that already have an identifiable economic purpose.
Florida Expands the Opportunity
On November 2, Rocket Doctor announced its launch in Florida, becoming the fourth U.S. state in which it operates, following California, New York and Maryland. More than twelve Florida-licensed physicians had already joined the platform at launch.
Florida represents an attractive market because of its large population and approximately nine million Medicare and Medicaid beneficiaries. Rocket Doctor also reports that around 24 million insured patients and plan members across California, New York and Maryland have in-network access to physicians using its platform.
These figures illustrate the potential reach of the business, but they require careful interpretation. Eligible populations are not equivalent to paying customers, and onboarding physicians does not guarantee substantial patient activity.
The financial value emerges when patients complete eligible consultations, claims are processed and payments are collected. Geographic expansion therefore represents an opportunity rather than proof of commercial success.
Florida gives Rocket Doctor another market in which to demonstrate its model. The important measures will be active physicians, completed consultations, revenue per visit and the efficiency of reimbursement collections.
Patient Visits Offer Early Evidence of Demand
Rocket Doctor's U.S. operating figures suggest growing adoption. Completed patient visits increased from 1,319 in the first quarter of 2026 to 3,911 in the second quarter and 6,101 in the third quarter.
That represents growth of approximately 362% between the first and third quarters, although from a relatively small base. Third-quarter visits increased roughly 56% sequentially, while U.S. clinical hours rose 33% to 2,634.
The company's Canadian operations provide additional scale. Rocket Doctor reported 47,247 completed Canadian patient visits during the third quarter, up 24% year over year. Combined U.S. and Canadian activity reached 53,348 visits.
These figures are encouraging because they measure actual clinical activity rather than theoretical market access. Nevertheless, patient visits are not interchangeable with revenue, particularly when reimbursement rates and collection schedules vary.
Rocket Doctor has explained that the increase in U.S. visits during the second quarter was not immediately reflected in reported revenue because of reimbursement timing. Management expects record third-quarter revenue as collections catch up with activity, but that remains a forecast until the financial results are reported.
The company's challenge is to demonstrate that growing patient activity produces sustainable economics. Revenue retained by the platform, physician compensation, patient acquisition costs and administrative efficiency will ultimately determine whether higher volumes translate into profitability.
Rocket Doctor's Financial Test
Rocket Doctor's second-quarter 2026 revenue reached approximately $734,000, an increase of 43% year over year, but remained broadly unchanged from the first quarter despite rising U.S. patient visits.
Gross margin was 65%, down from 75% in the preceding quarter, while the quarterly net loss widened to approximately $6.67 million. Its adjusted EBITDA loss reached $4.12 million.
These results illustrate the distance between operational momentum and financial maturity. Rocket Doctor is expanding clinical activity, but its expense base remains substantial relative to reported revenue.
At June 30, the company held approximately $950,000 in cash and cash equivalents. It subsequently raised roughly C$3.26 million through convertible debenture financing, providing additional resources while highlighting the continuing importance of capital availability.
Unlike Palantir, which generates substantial free cash flow, Rocket Doctor must finance expansion while improving collections and controlling costs. Additional financing may be necessary, potentially increasing debt obligations or diluting shareholders.
The next several financial reports will therefore be important. Stronger collections, rising revenue per physician and improving operating leverage would support the case that its growing network can become economically sustainable. Continued losses without corresponding financial progress would raise questions about the cost of expansion.
Rocket Doctor has demonstrated increasing clinical activity. It must now demonstrate that activity can support a profitable business.
Two Different Routes to the Same Commercial Destination
Palantir and Rocket Doctor are not competing for the same customers. Their products address different problems, and their financial characteristics are almost incomparable. The useful connection is where their software sits within activities that ultimately generate economic value.
Palantir sells institutional capabilities through substantial enterprise and government agreements. Its customers may justify those expenditures through improvements in productivity, coordination and decision-making.
Rocket Doctor operates closer to the delivery of an individual service. Physicians need patients, patients need accessible care, and insurers provide mechanisms for reimbursing eligible treatment. The company attempts to make those relationships function more efficiently.
Both models may develop competitive advantages through integration. Palantir becomes harder to replace as its platforms become embedded in organizational operations. Rocket Doctor could benefit as its physician network, payer relationships and patient activity reinforce one another.
But neither advantage is guaranteed. Palantir competes with enterprise software providers, cloud companies and customers developing internal AI capabilities. Rocket Doctor faces established telehealth competitors, reimbursement complexity, physician credentialing requirements and the considerable responsibilities associated with healthcare delivery.
Their financial positions also create very different investment risks. Palantir has already established substantial profitability, leaving investors to assess valuation and the durability of growth. Rocket Doctor remains an emerging business whose investment case depends on converting operational adoption into revenue and eventually positive cash flow.
Where the Next AI Winners May Emerge
As AI models become more capable and widely available, economic advantage may increasingly shift toward companies that control distribution, customer relationships and operational workflows.
A model can be licensed, integrated or replaced as technology evolves. Building a trusted commercial system around it is considerably more difficult, particularly when customers depend on that system for essential activities.
Palantir illustrates the institutional opportunity. Its platforms are integrated into complex operations, and its financial results demonstrate substantial customer willingness to pay. Rocket Doctor illustrates a more speculative alternative, building software around physicians, patients and established healthcare reimbursement.
The distinction matters for investors evaluating emerging AI companies. A large addressable market does not establish that a business can capture it, just as rising usage does not necessarily indicate attractive economics.
What matters is the progression from access to activity, from activity to revenue, and from revenue to sustainable cash generation. Palantir has already demonstrated that progression at scale, although its valuation introduces a separate challenge. Rocket Doctor has produced encouraging operating indicators, but its financial evidence remains incomplete.
The Real Test of Artificial Intelligence
The next phase of AI investing may be less concerned with identifying the most sophisticated model and more concerned with determining which businesses can make intelligent software economically indispensable.
Palantir has demonstrated how institutional AI adoption can translate into substantial contracts, revenue and profits. Rocket Doctor is testing whether physician-centered digital infrastructure can improve healthcare access while building a sustainable commercial platform.
The companies are different in almost every respect, but the underlying economic principle is the same. Technology creates lasting value when it solves a problem that matters to customers and operates within a reliable payment system.
The enduring winners of the AI economy may therefore be defined less by what their models can do than by where those models are deployed, who depends on them, and whether the resulting activity generates revenue that ultimately becomes profit.
Neural Capital receives no payment, sponsorship or compensation from Palantir Technologies, Rocket Doctor AI, or any other company mentioned in this article. This publication is intended solely for independent editorial and informational purposes and does not constitute investment advice or a recommendation to buy or sell securities.
Readers should conduct their own due diligence, review official financial disclosures and consider their individual financial circumstances before making investment decisions. The companies discussed have substantially different financial profiles, risk characteristics and stages of commercial development.
Want to invest in PLTR?
Visit our How to Invest page to get started with platforms like Fidelity or Robinhood.
Disclosure: This article is editorial and not sponsored by any companies mentioned. The views expressed in this article are those of the author and do not necessarily reflect the official policy or position of NeuralCapital.ai.